

RCI Hospitality (RICK) has been one of our more controversial investments over the past year.
The stock suffered a major selloff alongside other restaurant and hospitality stocks, such as Chipotle (CMG) and Cava (CAVA), as investors became increasingly concerned about weakening consumer spending. But RICK’s decline was made worse by legal allegations against the company, while rising financing costs and increased leverage added further pressure:
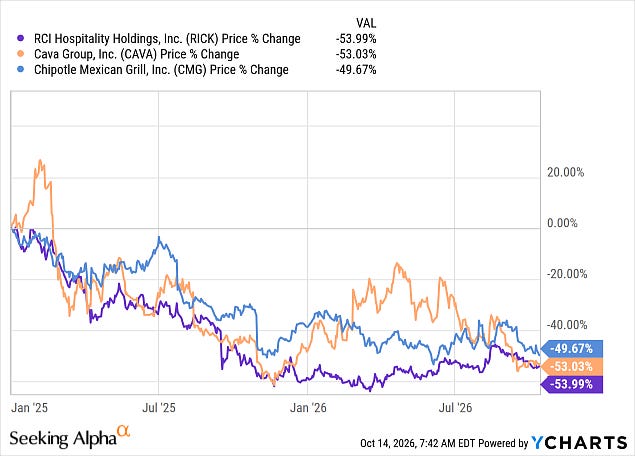
But I have maintained that the underlying business is worth considerably more than what the market is willing to pay for it. Earlier this year, we increased our position by about 10%, after RICK finally released its delayed financial statements and provided greater clarity on its financial position.
The stock has since recovered a little, but it remains deeply discounted. I recently had the opportunity to speak with Eric Langan, RICK’s founder and former CEO, who remains involved as Head of M&A. During our nearly one-hour conversation, we discussed the legal case, debt, real estate sales, operating performance, acquisitions and buybacks.
I came away encouraged. The problems are real, but there is a clearer potential path toward resolving them, restoring financial flexibility, and returning to the growth strategy that made RICK so successful historically. Given the valuation, the upside could be substantial if management executes.
Here are my main takeaways.