

Quick Reminder:
I am excited to announce that we will be hosting our fifth live Q&A webinar, exclusively for subscribers of High Yield Landlord.
This is your opportunity to connect directly, ask questions, and dive deeper into REITs, real estate, and anything else we cover in the newsletter.
Event Details
Format: Live Zoom Q&A
Date & time: Monday 10/05/2026 at 1PM EST
Spots available: Only 300 — first come, first served
How It Works
You will be able to ask questions live in the Zoom chat during the session
You can also leave your questions in the comment section below in advance — I will try to answer as many as possible
If you cannot attend live, I will post a recording afterward for all subscribers
Reserve Your Spot
Due to limitations in our Zoom plan, we can only accommodate 300 participants for the live session.
If you would like to attend live, please reserve your spot as soon as possible — click here to register.
Looking forward to seeing many of you there!
Our New Top Pick: National Health Investors
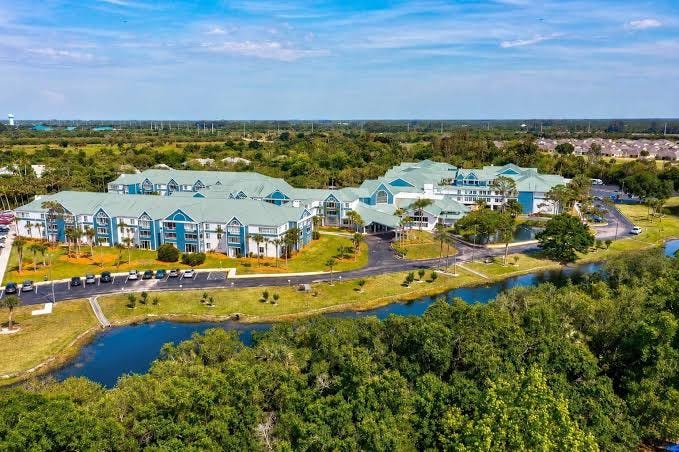
National Health Investors (NHI) has made multiple shareholder-friendly moves recently for which the REIT has scarcely been rewarded by the market.
The REIT currently trades at a 13.1x FFO multiple (based on normalized FFO per share), which is near the lower end of its range from the last few years.
We certainly think this is too low given NHI’s recent capital allocation moves and future growth prospects. We think the REIT deserves at least an 18x FFO multiple, giving it 30% upside to fair value. That’s on top of a 5.8% yield and mid-single-digit growth rate.
Since we have covered NHI multiple times recently, let’s emphasize some of this year’s most important highlights:
The sale of the 35 master-leased properties (mostly skilled nursing and a few independent living facilities) operated by National Healthcare Corporation back to the tenant was completed in July 2026. This generated $560 million in proceeds at a roughly 7% cap rate.
Critically, this deal eliminated conflicts of interest between NHI and NHC, which had some overlap in board membership.
In addition to the NHC sale, NHI has also completed 6 other property dispositions for $117 million at an average cap rate of 8.4%. Judging by the exit yield, these were some of NHI’s lower-quality properties.
So far this year, NHI has acquired $237 million of real estate, $212 million of which was SHOP (senior housing operating properties), and had signed letters of intent for another $127 million. The weighted average yield on 2026 investments is 7.74%, while signed LOIs yield 6.5%.
Private pay senior housing has now reached almost 80% of the portfolio, up from ~66% in Q2 2025.
Net debt to EBITDA sat at 4.1x in Q2, but pro forma (once recent disposition proceeds are reinvested), it is a mere 2.5x.
We think NHI temporarily trades at a discount to our estimated fair value because management’s portfolio recycling efforts are causing a very slight dip in FFO per share this year. But in the long run, these portfolio moves will result in a much stronger portfolio that is capable of faster organic growth.
We expect NHI to generate 5-8% FFO per share growth in 2027 and beyond.
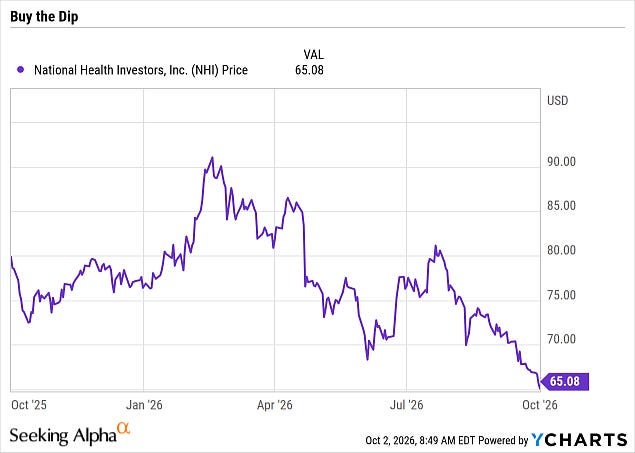
The current dip in the stock price represents a great buying opportunity for long-term investors.
