

Quick Reminder:
We just held our quarterly webinar and discussed many of our top holdings, recent trades, and the opportunities that we are most excited about today.
Many of you joined us live, and I want to thank you for taking the time and for asking such thoughtful questions.
Here is a list of topics with timestamps for your convenience:
0:56 - Rising interest rates
5:12 - Realty Income (O)
7:16 - Essential Properties Realty Trust (EPRT)
9:16 - Agree Realty Corporation (ADC)
11:08 - Cash secured puts and covered calls
12:30 - Cibus Nordics (CIBUS)
13:33 - Tallinna Sadam (TSM1T)
15:15 - European REITs
17:20 - Branicks (BRNK)
19:35 - Canadian REITs
21:06 - Vital Infrastructure Property Trust (VITL.UN:CA)
23:10 - 5 REITs that are heavily discounted to NAV
25:05 - Current favorite REIT sectors
26:46 - Temporary crisis or permanent change in interest rate expectations
28:55 - CTP and Hamborner REIT
30:25 - ARMOUR Residential REIT (ARR)
31:23 - AH Realty Trust (AHRT)
34:15 - Accelerating rent growth
36:30 - Cold storage REITs
37:05 - Unite Group vs. Xior Student Housing
38:00 - Rising government debt levels
39:30 - Top REITs for the next 12 months
41:40 - Safehold (SAFE)
42:30 - Patria Investments (PAX)
44:30 - Realty Income (O)
45:10 - Agree Realty Corporation (ADC)
47:00 - Favorite Apartment REIT today
48:25 - Clipper Realty (CLPR)
49:40 - European vs. US REITs
51:45 - Agree Realty Corporation (ADC)
52:15 - Wynn Resorts (WYNN)
53:10 - RCI Hospitality (RICK)
54:40 - NewLake Capital Partners (NLCP)
56:10 - VICI Properties (VICI) vs. REIT Preferred Shares
58:20 - Best property sectors for a higher-for-longer environment
59:10 - Residential oversupply in Sunbelt markets
1:00:27 - Invitation Homes (INVH)
1:03:08 - Net Lease Office Properties (NLOP)
1:03:53 - NewLake Capital Partners (NLCP)
1:04:30 - Alexandria Real Estate (ARE)
1:06:55 - Kite Realty Group (KRG) vs. Kimco Realty (KIM)
1:07:25 - Closing Notes
TRADE ALERT - Core Portfolio October 2026
Since initiating our position in Blackstone Digital Infrastructure Trust (BXDC), the investment thesis has not changed.
What has changed is the price.
The broader REIT market has sold off sharply as the escalation of the war pushed energy prices and inflation higher, ultimately forcing the Fed to hike interest rates. BXDC has been dragged down with the rest of the sector and has now fallen by roughly 16% since we initiated our position.
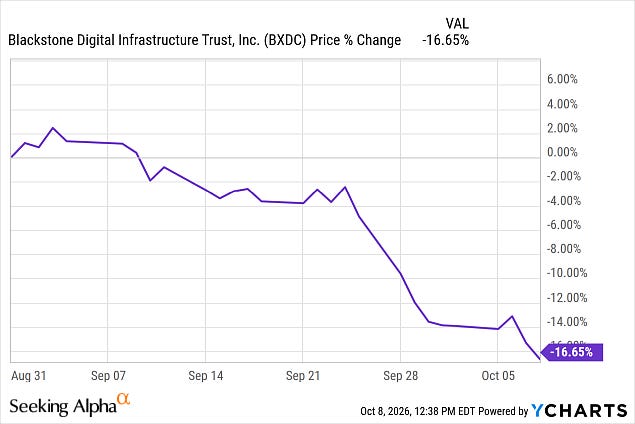
We view this as an attractive opportunity to buy the dip, and we are therefore increasing the size of our BXDC position today.

BXDC completed its IPO earlier this year at $20 per share. The stock is now trading at around $17, or roughly 16% below its IPO price.
Importantly, however, the recent increase in interest rates has had very little direct impact on the company itself.
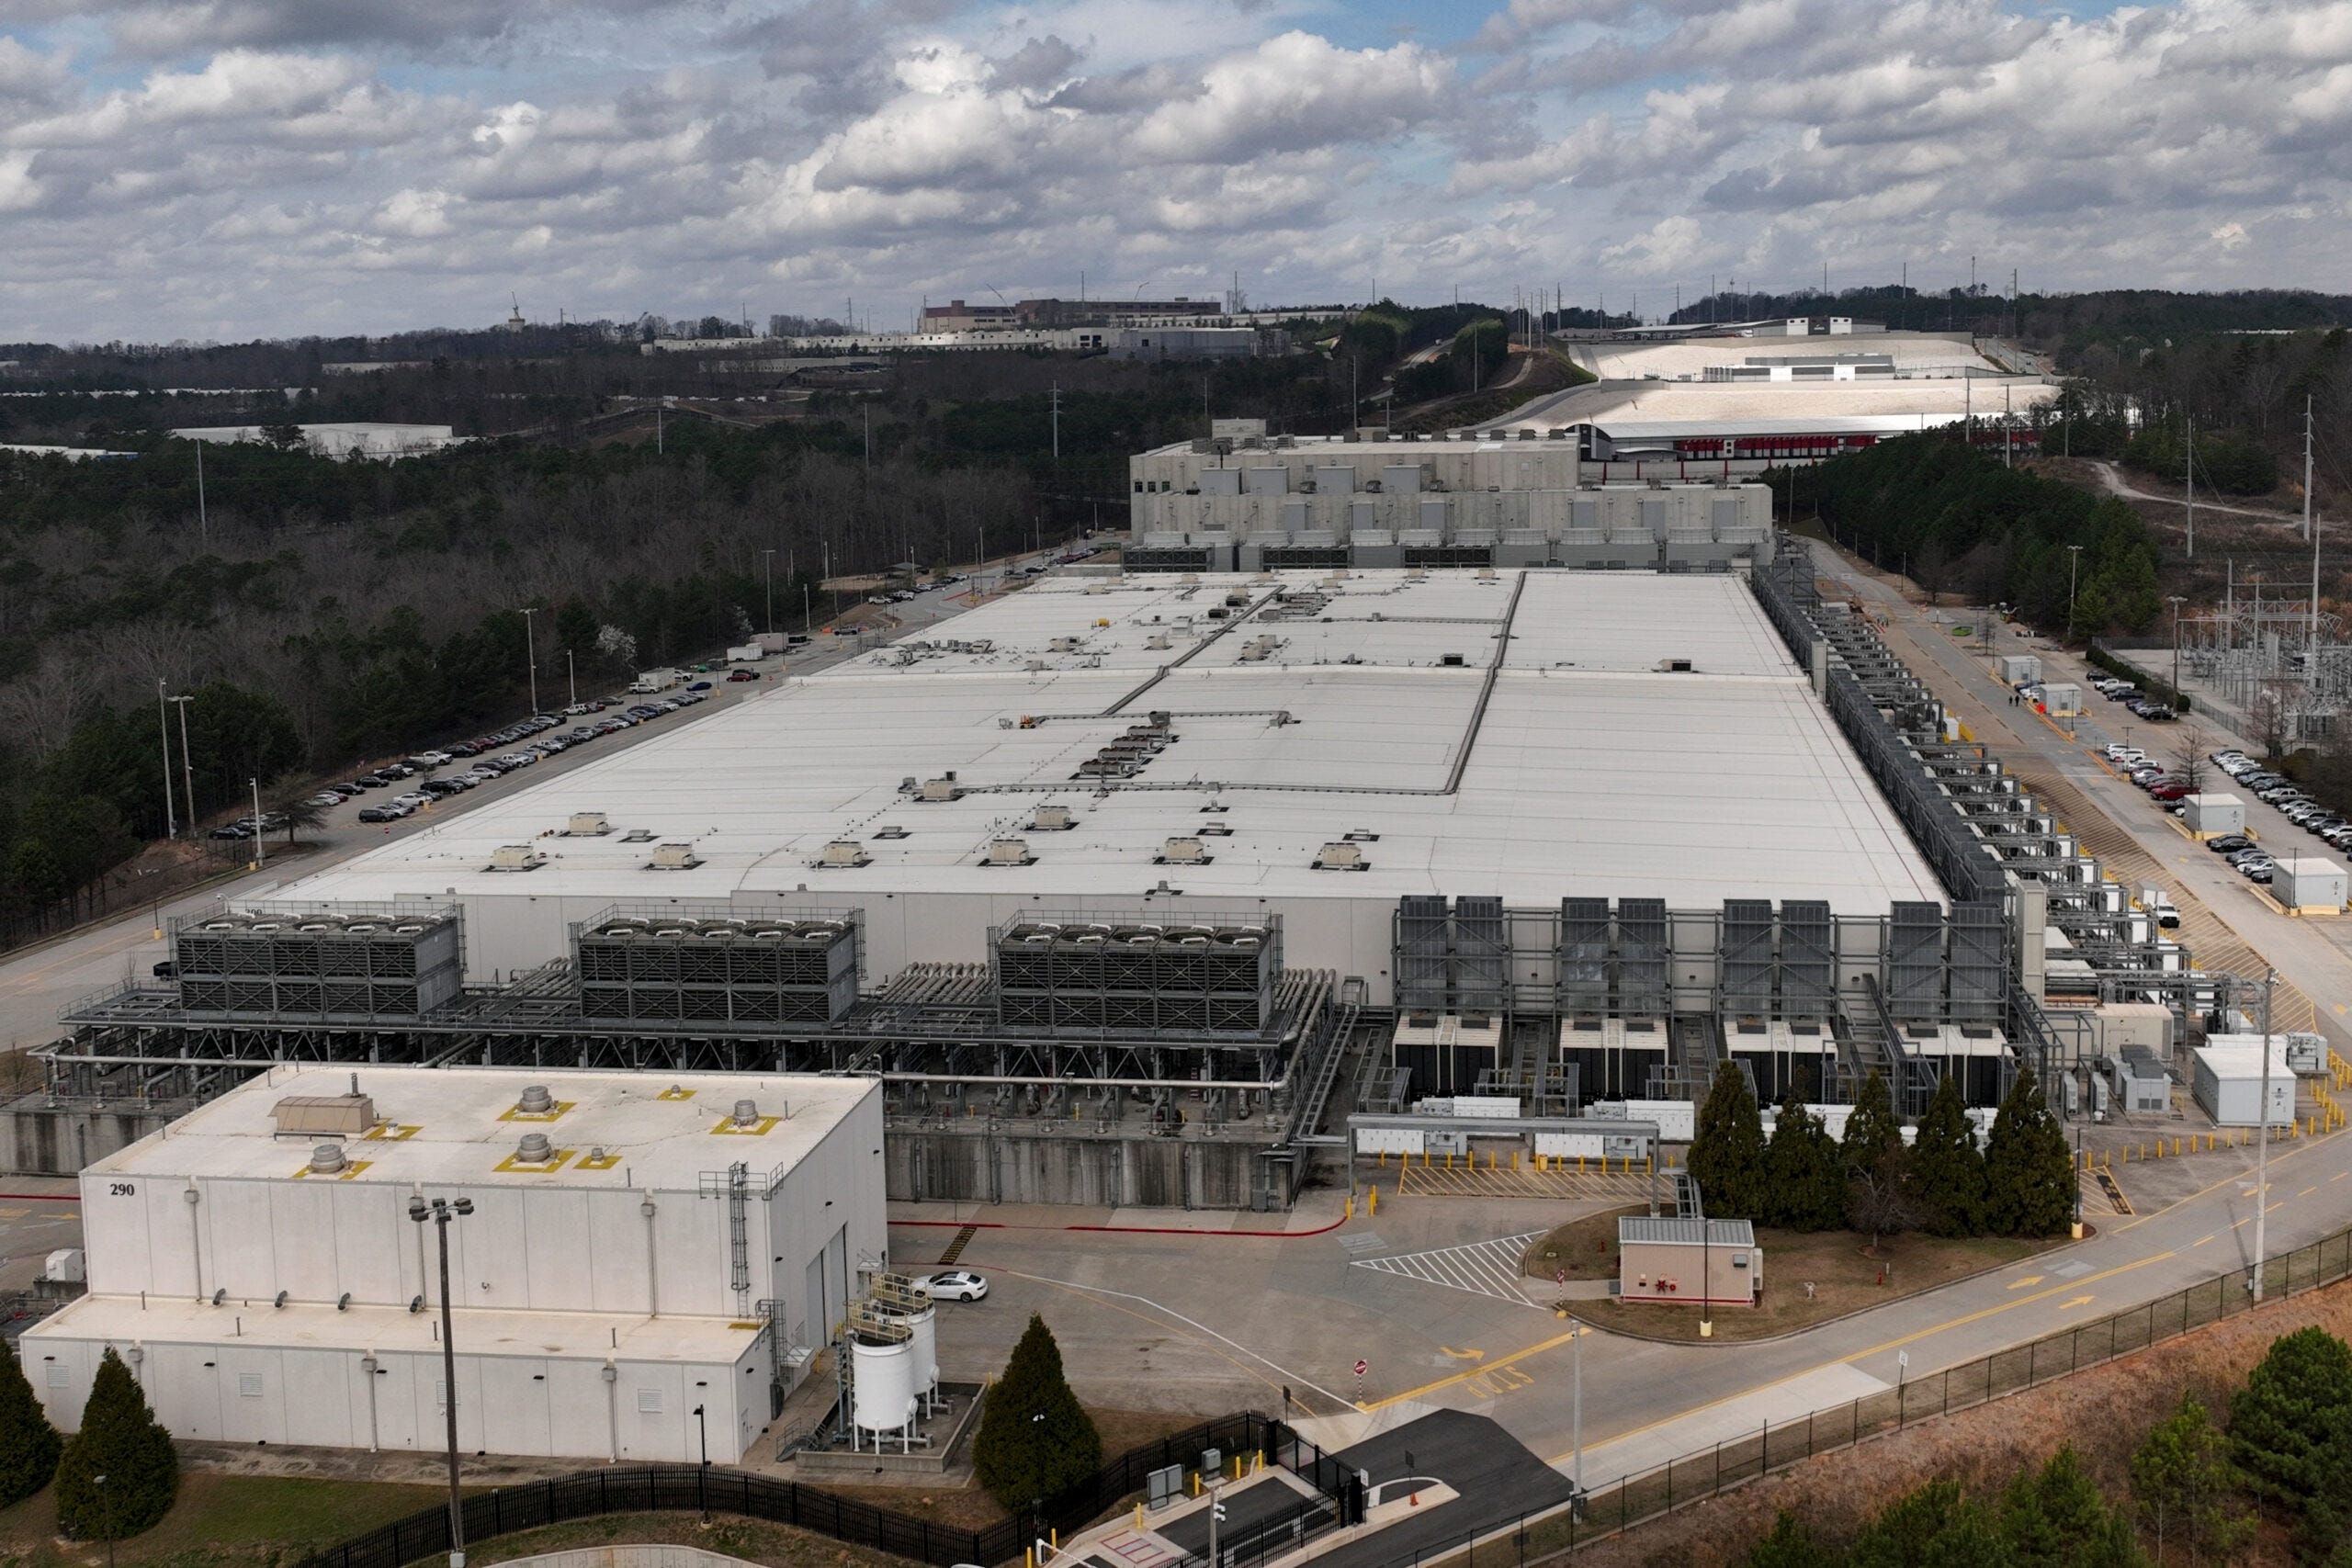
BXDC is in a very unusual position today because it has barely built its portfolio yet.
As of the end of the second quarter, BXDC had approximately $1.94 billion of cash and cash equivalents and had not yet acquired any data centers. It also had no outstanding borrowings under its credit facility.
With roughly 100.6 million shares outstanding, that works out to about $19.30 of cash per share.
Yet the stock is now trading at roughly $17.
Put differently, we are essentially getting the opportunity to buy this pile of cash at an approximately 13% discount before Blackstone has even had the opportunity to deploy most of it into data centers.
Of course, there are fees, expenses, and execution risks, so I would not treat this as literally buying $1 of cash for $0.87. But it illustrates why we think the recent sell-off is particularly interesting in BXDC’s case.
BXDC does not have a leveraged legacy portfolio that is now suffering from higher refinancing costs. It has no meaningful debt today and is still sitting on nearly all of the capital that it raised in its IPO.
That gives it a lot of optionality.
Blackstone intends to deploy this capital into newly constructed, stabilized data centers leased primarily to investment-grade hyperscalers on long-term contracts.
And interestingly, the recent rise in interest rates could actually make the opportunity set somewhat more attractive.
When we first invested, BXDC was targeting acquisition yields of roughly 5.75%-7%+, depending on the assets. If higher rates put some pressure on private real estate valuations, Blackstone may now be able to deploy some of this capital at somewhat higher cap rates than would otherwise have been possible.
We do not know yet whether that will happen, and we do not want to assume it. But BXDC enters this higher-rate environment from a very different position than most REITs.
It is primarily a buyer of assets rather than an owner of a large leveraged portfolio that needs to refinance debt.
That distinction is important.
The company can remain patient, earn interest on its cash while it waits, and potentially take advantage of more attractive acquisition opportunities if higher rates create them.
During the roughly six weeks between its IPO and the end of June, BXDC already generated $9.3 million of interest income from its cash holdings. With short-term rates now higher, the yield earned on this undeployed capital should, all else equal, also be somewhat more attractive while Blackstone waits for the right opportunities.
The bigger opportunity, however, remains what happens once the cash is invested.
