

We have been looking for opportunities to increase our international exposure. With the world facing unusually high geopolitical and economic uncertainty, including in the U.S., we think it makes sense to spread our investments across more countries, currencies, and property markets rather than concentrating all our bets in one basket.
Today, we are doing exactly that by initiating a new small position in Canadian Apartment Properties REIT (CAR.UN:CA; CDPYF) for our International Portfolio. As new capital becomes available, we expect to grow it into a larger position over time:

CAPREIT is Canada’s largest publicly traded apartment landlord, with more than 45,000 apartment units, worth about C$14.4 billion. Most of its value is concentrated in attractive urban markets such as Toronto, Vancouver, Victoria, and Montreal. Yet the recent sector selloff has pushed its shares to around C$31, a roughly 43% discount to its latest reported NAV of C$54.38 per unit.
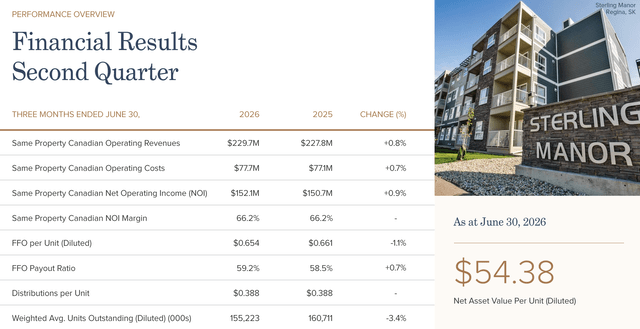
At this price, we get a nearly 5% distribution yield, an FFO multiple of roughly 12x, ongoing share repurchases, and what we believe is considerable upside as Canada’s rental market eventually recovers. We do not expect much growth immediately, but we believe the five- to ten-year opportunity is compelling.
We Have Done Very Well With Canadian Apartment REITs
Long-time members will know that Canadian apartments have been a particularly profitable hunting ground for us.
Our first investment was Northview Apartment REIT, which we bought in 2018 when its properties were trading at what we considered a substantial discount to private-market value. It was subsequently bought out, allowing us to realize a 54% total return despite the turmoil caused by the pandemic.
We then reinvested the proceeds into Boardwalk REIT (BEI.UN:CA). At the time, we considered Boardwalk the best opportunity in Canadian apartments. We held it through a significant recovery in its fundamentals and valuation, eventually selling once it reached our fair value estimate and realizing a 157% total return.
More recently, we bought Northview Residential REIT (NRR.UN:CA) at roughly C$9 per unit. Its shares have declined lately along with the sector, but at around C$13–14, we are still sitting on a substantial unrealized gain. We continue to own it and remain optimistic about its prospects.
Those have been three well-timed investments in a sector we have followed closely for years. Of course, past returns do not guarantee future results. But we believe our familiarity with these companies, their management teams, financing structures, and underlying property markets helps us identify opportunities when sentiment becomes excessively negative.
We now think CAPREIT could become another highly profitable Canadian apartment investment for us. What’s different this time is that some of the highest-quality, large-city portfolios have finally become just as discounted as the riskier alternatives.
A Selloff So Severe That Private Buyers Have Stepped In
Canadian apartment REITs have suffered a prolonged selloff, in some cases worse than their U.S. counterparts. One reason is that Canadian REITs commonly operate with higher debt-to-EBITDA ratios than large U.S. apartment REITs. As interest rates rose, refinancing became more expensive, and investors worried about how much cash flow would remain for shareholders.
The other major concern is the rental market itself. Canada sharply reduced temporary immigration, particularly student and foreign-worker inflows, just as apartment developments initiated during the earlier boom were being completed. That has weakened rental demand and asking rents in several large cities.
Public investors have reacted harshly. Private real estate buyers, however, have been taking a different view.
InterRent REIT agreed to be acquired by CLV Group and GIC, Singapore’s sovereign wealth fund, for C$13.55 per unit, a 35% premium to its unaffected share price. Minto Apartment REIT was acquired by Crestpoint Real Estate Investments and Minto Group for C$18 per unit, a 32% premium to its last unaffected closing price.
Both transactions were completed in 2026. They demonstrate that sophisticated institutional investors see substantial value in Canadian rental properties at prices meaningfully above those quoted in the stock market.
Meanwhile, several remaining publicly traded apartment REITs have continued to decline to even lower levels. That is why we have taken another close look at the entire sector.
