

Quick Note:
I just shared an important announcement that I think you should read if you missed it.
---------------------------------------------------
TRADE ALERT - Retirement Portfolio November 2026
We are buying more shares of EPR Properties’ Series G Preferred Shares (EPR.PR.G) for our Retirement Portfolio.

What makes this opportunity especially interesting today is that we think the preferred shares have become temporarily mispriced because of an unusually large sale in a very illiquid security.
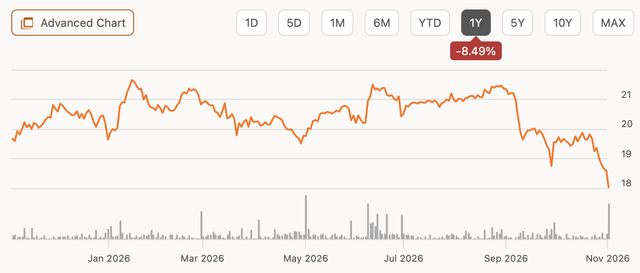
EPR.PR.G was already declining along with most preferred shares as interest rates moved higher, but on November 2, an unusually large amount of stock hit the market. More than 56,000 shares traded, compared with only a few thousand shares on many normal days, pushing the preferred below $18.00.
There was no corresponding deterioration in EPR’s fundamentals. Quite the opposite: EPR had just reported a strong third quarter, and its common stock actually rose on the same day.
To us, this looks much more like an illiquidity-driven dislocation than a fundamental reassessment of EPR’s credit quality, and that is why we are buying more today.
An Illiquidity-Driven Opportunity
The preferred equity segment of the REIT market is much less liquid than the common equity market, and this can occasionally create unusually attractive opportunities.
When interest rates surge, some preferred shareholders rotate capital into Treasuries, corporate bonds, or other fixed-income securities that suddenly offer more competitive yields. In a common stock with millions of shares trading every day, this selling can usually be absorbed relatively easily. In a small preferred issue, however, even one large seller can overwhelm the available bids and push the price down sharply.
We think that is exactly what happened here.
The broader backdrop also helps explain why the shares were already weak before this latest block sale. Preferred shares are essentially bond-like securities with fixed dividends, so when interest rates rise, their prices tend to decline so that their yields remain competitive with newly issued fixed-income securities.
REIT preferred equities have therefore sold off in recent months, and in many cases, they have declined just as much as, if not more than, the common equities of their issuers.
As a result, we can now exceptionally find preferred shares issued by investment-grade-rated REITs offering yields of 7-8%, despite highly predictable underlying cash flows, strong balance sheets, and very substantial preferred dividend coverage. Outside of recessions and periods of severe market stress, yields this high have historically been unusual.
EPR.PR.G stands out even within this already attractive group because the latest selling has pushed it down much further. At roughly $18, the shares are now trading around levels not seen in years.
We cannot know whether the seller is completely done, and the shares could certainly fall further if rates keep rising. But for our Retirement Portfolio, where our priority is generating sustainable income while limiting downside risk, this is exactly the type of temporary dislocation that we want to take advantage of.
