

This week, we continue to buy the dips.
As always, we are not attempting to perfectly time the bottom. That is impossible. Instead, we are gradually making small additions across a number of our favorite REITs as opportunities present themselves.
Our focus is on REITs that have suffered significant share price declines, but still have strong balance sheets, high-quality properties that are in-demand, and compelling long-term growth prospects.
There are a lot of attractive opportunities right now, and so rather than make one big bet, we think it makes more sense to slowly accumulate larger positions over time while valuations remain depressed.
This week, we are buying two REITs for our Retirement Portfolio, two for our Core Portfolio, and two for our International Portfolio.
Why We Are Buying the Dip
We recently published a detailed Market Update explaining why we think that the latest selloff is creating a particularly attractive buying opportunity.
Until recently, the market had been expecting the Fed to remain on pause. But following the escalation of the war in Iran and the resulting surge in oil prices and inflation, expectations have rapidly shifted toward additional rate hikes. REITs, as you would expect, have sold off as a result.
But importantly, we don’t think that this changes the long-term thesis.
The inflationary surge remains overwhelmingly driven by energy prices. Core inflation has continued to follow a much more encouraging disinflationary trajectory, and most major categories outside of energy are showing either stable or falling inflationary pressures.
We therefore continue to view this primarily as a geopolitical energy shock rather than the beginning of a new structural inflationary cycle.
Even more importantly for REITs, the surge in interest rates is making new real estate development increasingly difficult.
Construction lending has already fallen sharply, development pipelines have collapsed across a number of property sectors, and every additional month of high rates makes it harder for developers to justify new projects.
This creates an interesting paradox.
Higher interest rates are clearly negative for REIT valuations in the short run. But at the same time, they are extending the period of limited new construction, which should strengthen the pricing power of existing landlords in the years ahead.
The market is focused almost entirely on the first part of this equation. We think it is underestimating the second.
That is why we are buying, but we aren’t buying just any REIT.
We particularly like REITs that:
Have suffered unusually large dips.
Have strong balance sheets and therefore aren’t heavily exposed to higher financing costs.
Own properties that remain in strong demand.
Operate in sectors where new supply is likely to become increasingly constrained.
Trade at significant discounts to the value of their underlying real estate.
Here are the six names we are buying this week.
Retirement Portfolio
Agree Realty Corporation (ADC)
We are buying more shares of Agree Realty.
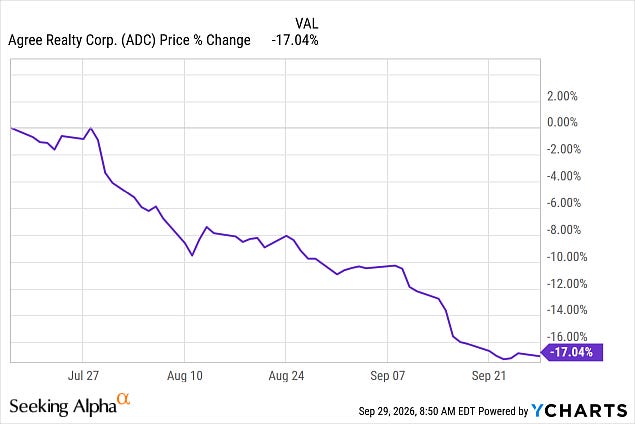
ADC has been hit particularly hard in the recent selloff. Its shares have fallen roughly 17% from their 52-week high, making it one of the steeper recent declines in the net lease sector. At the current share price, its $3.204 annualized dividend translates into a yield of roughly 4.8%.
We recently had the opportunity to interview ADC’s management, and the key point is that very little has changed fundamentally. You can read the interview by clicking here.
The business continues to perform exceptionally well.
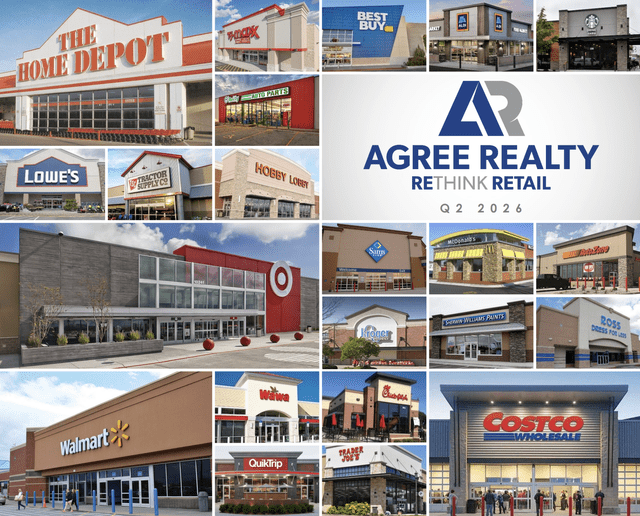
Its portfolio was 99.8% leased at the end of the second quarter, roughly two-thirds of its rents came from investment-grade tenants, and AFFO per share grew by 7.4% year-over-year during the quarter. Management actually raised its 2026 AFFO-per-share guidance and now expects roughly 5.8% growth at the midpoint.
Its balance sheet is also exceptionally strong.
Debt-to-EBITDA was just 3.7x at the end of the second quarter, and the company had roughly $1.9 billion of liquidity. Importantly, this included about $1.1 billion of already-raised but unsettled forward equity. In other words, ADC has already secured a large amount of the equity capital that it needs to fund future acquisitions.
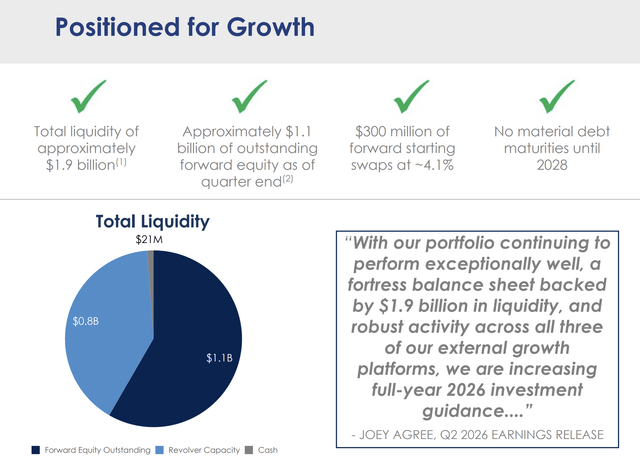
This puts it in a particularly attractive position today.
Higher interest rates may push acquisition cap rates even higher and improve investment spreads, but ADC does not need to issue large amounts of new equity at today’s depressed share price to take advantage of these opportunities.
It was already acquiring properties at a 7.0% weighted-average cap rate in the second quarter and has raised its full-year investment guidance to $1.6-$1.8 billion.
So you have a REIT with low leverage, a defensive portfolio, strong growth, significant pre-funded acquisition capacity, and a nearly 5% dividend yield.
Yet its share price has dropped sharply.
We think that this is a great buying opportunity.
